
Loading
Loading
We use strictly necessary cookies to run this site, and analytics cookies to understand how it's used. See our Privacy Policy for details.
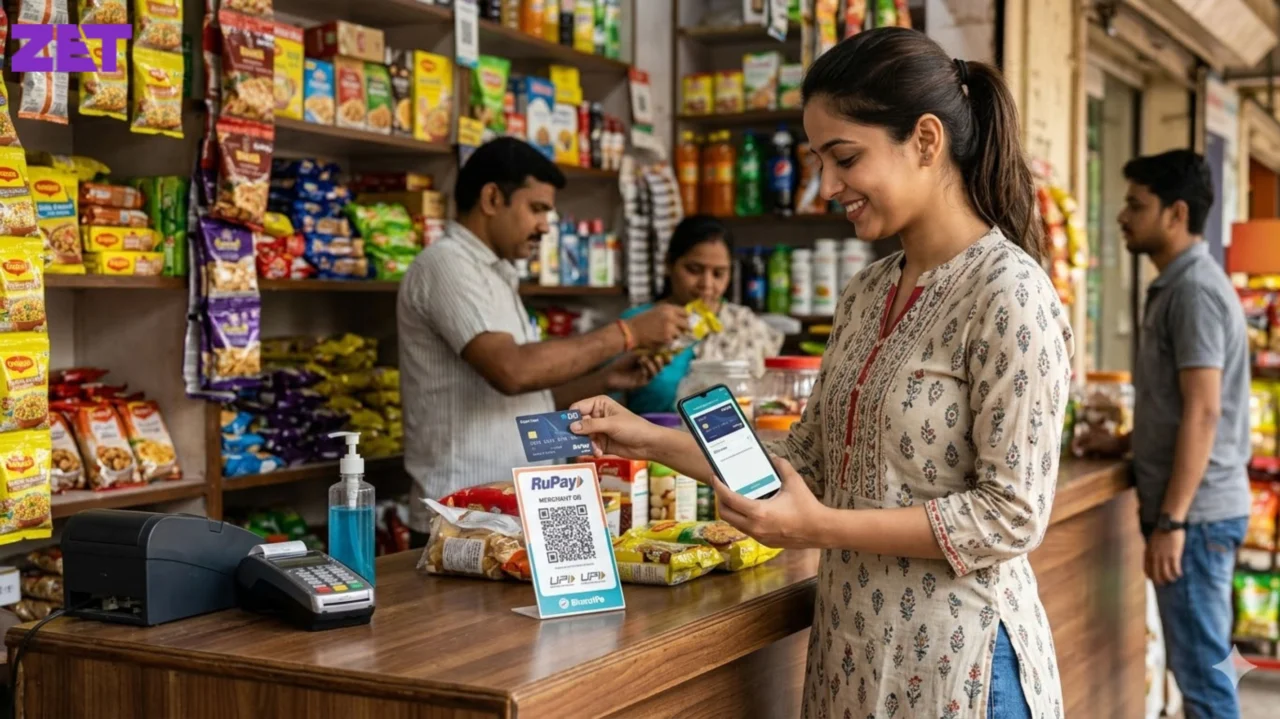
India’s digital payments story has become one of the clearest examples of how technology, public policy and mass participation can come together to transform everyday life.
Summary
What was once considered a technology-driven experiment has now become a routine part of the Indian economy, with shopkeepers, farmers, students, small businesses and street vendors using digital payments within seconds. At the centre of this transformation is the Unified Payments Interface (UPI), backed by a wider digital ecosystem built around bank accounts, mobile connectivity, Aadhaar and digital public infrastructure. UPI has changed how Indians pay The scale of UPI’s expansion highlights how deeply digital payments have entered India’s economic life.
In August 2026, UPI recorded 752 million transactions, with the total value of transactions reaching nearly Rs 29.82 lakh crore. The numbers demonstrate more than the popularity of one payment platform. They point to a fundamental shift in how Indians conduct everyday economic activity.
From paying for groceries and transport to transferring money to family members and making business payments, transactions that once required cash can now be completed digitally within seconds. For small businesses in particular, digital payments have reduced dependence on cash and made it easier to maintain transaction records. For consumers, they have brought speed and convenience into routine financial activity.
The transformation has also demonstrated that advanced digital infrastructure can be deployed on a massive scale without restricting access to urban or affluent populations. PM Modi’s focus on digital inclusion Prime Minister Narendra Modi has consistently presented digital technology as a tool for financial inclusion and citizen empowerment, rather than simply as a technological achievement. The broader digital ecosystem has brought together several important components.
Bank accounts have expanded access to formal financial services, mobile connectivity has made digital services more accessible, Aadhaar has strengthened digital identity infrastructure, and platforms such as UPI have enabled instant payments. Together, these developments have helped bring millions of people closer to the formal financial system. The significance of this approach lies in its focus on making technology useful in the daily lives of ordinary citizens.
Digital infrastructure becomes meaningful when a small vendor can receive a payment instantly, a worker can transfer money to family members without visiting a bank, or a small entrepreneur can conduct business digitally. Also Read: Bangladesh: Made-in-China tank explodes during military exercise, 2 soldiers killed, 1 officer seriously injured The next fintech revolution goes beyond payments While UPI remains the most visible symbol of India’s fintech success, the next phase of the transformation is expected to extend much further. Fintech is increasingly being used to make credit, insurance, savings, investments and pension products more accessible.
For a small entrepreneur, easier access to formal credit can provide the capital needed to expand a business. For farmers, accessible insurance can provide protection against unexpected losses. For young Indians, digital savings and investment tools can make it easier to begin building long-term financial security.
This means fintech is gradually moving from being primarily about how people pay to influencing how people save, borrow, invest and protect their financial future. That broader transformation could have an even greater impact on financial inclusion. India wants to move from user to global innovator The focus is now shifting from adopting digital technology to developing the technologies that will shape the next generation of finance.
The Global Fintech Fest 2026 is an important platform in this transition, with emerging areas such as Agentic AI, tokenisation, quantum technology and trusted digital systems becoming part of the fintech conversation. These technologies could reshape financial services in areas ranging from automated financial decision-making to digital assets, security and transaction infrastructure. For India, the larger ambition is clear: the country does not want to remain only one of the world’s largest users of digital financial services.
It wants to become a global centre for fintech innovation. India’s digital model is drawing global attention India’s fintech experience has also increased the country’s influence beyond its domestic financial system. The country’s digital public infrastructure demonstrates that large-scale financial technology can be designed around accessibility, affordability and inclusion.
For developing economies, India’s experience offers a potential model for creating digital systems that can connect large populations to financial services without requiring expensive traditional infrastructure at every stage. The international significance of India’s fintech journey therefore goes beyond UPI itself. It lies in the broader idea that digital public infrastructure can become a foundation for economic participation.
Also Read: Ujjain’s Khade Hanuman ji’s Murti refuses to budge, leaving authorities in a fix Cybersecurity and data protection will become critical Rapid digitalisation, however, also brings new risks. As more financial transactions and services move online, cybersecurity, data protection, fraud prevention and consumer safety become increasingly important. A digital financial system can succeed only when people trust it.
Citizens need confidence that their money, financial information and personal data are protected. This makes responsible regulation as important as technological innovation. The future of fintech will therefore require close cooperation between the government, regulators, financial institutions and technology companies.
Strong security systems, responsible use of data and effective consumer protection will have to grow alongside innovation. Trust will shape the future of digital finance The next stage of India’s fintech journey cannot be based only on transaction volumes or technological breakthroughs. Trust will be equally important.
Consumers need to understand how digital financial products work and how their data is being used. Businesses need secure systems that protect them against fraud. Regulators need to ensure that innovation does not come at the expense of consumer rights.
A stronger focus on financial awareness and consumer protection can help ensure that India’s digital transformation remains sustainable. The challenge is particularly important as increasingly sophisticated technologies, including artificial intelligence, become part of financial decision-making. Strong economy creates more space for fintech growth India’s broader economic performance also provides an important backdrop to this transformation.
The country recorded 7.8 per cent growth in the April-June quarter, despite continuing global economic uncertainties.
This summary is a partial excerpt, the source's own feed cuts off here. Read the full story at Organiser Weekly for the rest.
KazaSec's take
AI-related security incidents are a genuinely new category, prompt injection, model manipulation, and data leakage through an LLM integration don't map cleanly onto traditional application security testing, and are worth assessing deliberately rather than assuming existing controls already cover them.
Coverage details
We've archived 72 other articles touching the same topic (upi india, upi transactions 2026, pm modi fintech vision) , see the full security news archive.
Relevant from KazaSec
More coverage on this topic
We help organizations find and fix the gaps before they make headlines.